Initial claims for unemployment insurance rose last week but held at levels consistent with how the job market looked before the Covid-19 pandemic devastated the U.S. employment picture, the Labor Department reported Thursday.

First-time filings for the week ended Nov. 27 totaled 222,000, less than the 240,000 Wall Street expected. That was higher than the 194,000 from the previous week, but that total, the lowest since 1969, was revised even further down from the initial 199,000 reported.

The totals are the product of heavy seasonal adjustments, though the unadjusted number was actually lower, at 211,896.

The report comes amid signs of an increasingly tight labor market, with workers leaving their positions for new jobs at the highest level on record and with hiring persisting at a brisk pace.

In addition to the brightened outlook for initial claims, continuing claims fell by another 107,000 and are now below 2 million for the first time since the early days of the pandemic. The last time continuing claims, which run a week behind the headline number, were lower than the current 1.96 million was March 14, 2020.

Virginia and Texas combined to see more than 15,000 fewer claims filed for the week, according to unadjusted data.

Thursday’s report comes a day ahead of the closely watched nonfarm payrolls count from the Bureau of Labor Statistics.

That tally is expected to show an addition of 573,000 new jobs in November, following a gain of 531,000 in October. The unemployment rate is expected to edge lower to 4.5%.

Correction: Jobless claims for the previous week were initially reported as 199,000. An earlier version misstated the figure.
Read More

Enterprise resource planning (ERP) tools are some of the most commonly used workflow and operations management options. In its most basic terms, ERP software consolidates various business processes, such as human resources, accounting, or other ongoing management functions. There are really many kinds of ERP platforms out there. Some are designed specifically for certain industries, […]

The post Making The Most of Your ERP Software appeared first on Entrepreneurship Life.

Read More

Thanks to the constant sunshine, miles of white sand beaches, and world-renowned cuisine, Miami and South Florida have long been known as some of the most popular destinations for vacationers and residents.  However, many people don’t realize that South Florida’s popularity extends to the real estate market as well.  South Florida homes sell faster than […]

The post Why South Florida’s Housing Market is Always Hot? appeared first on Entrepreneurship Life.

Read More

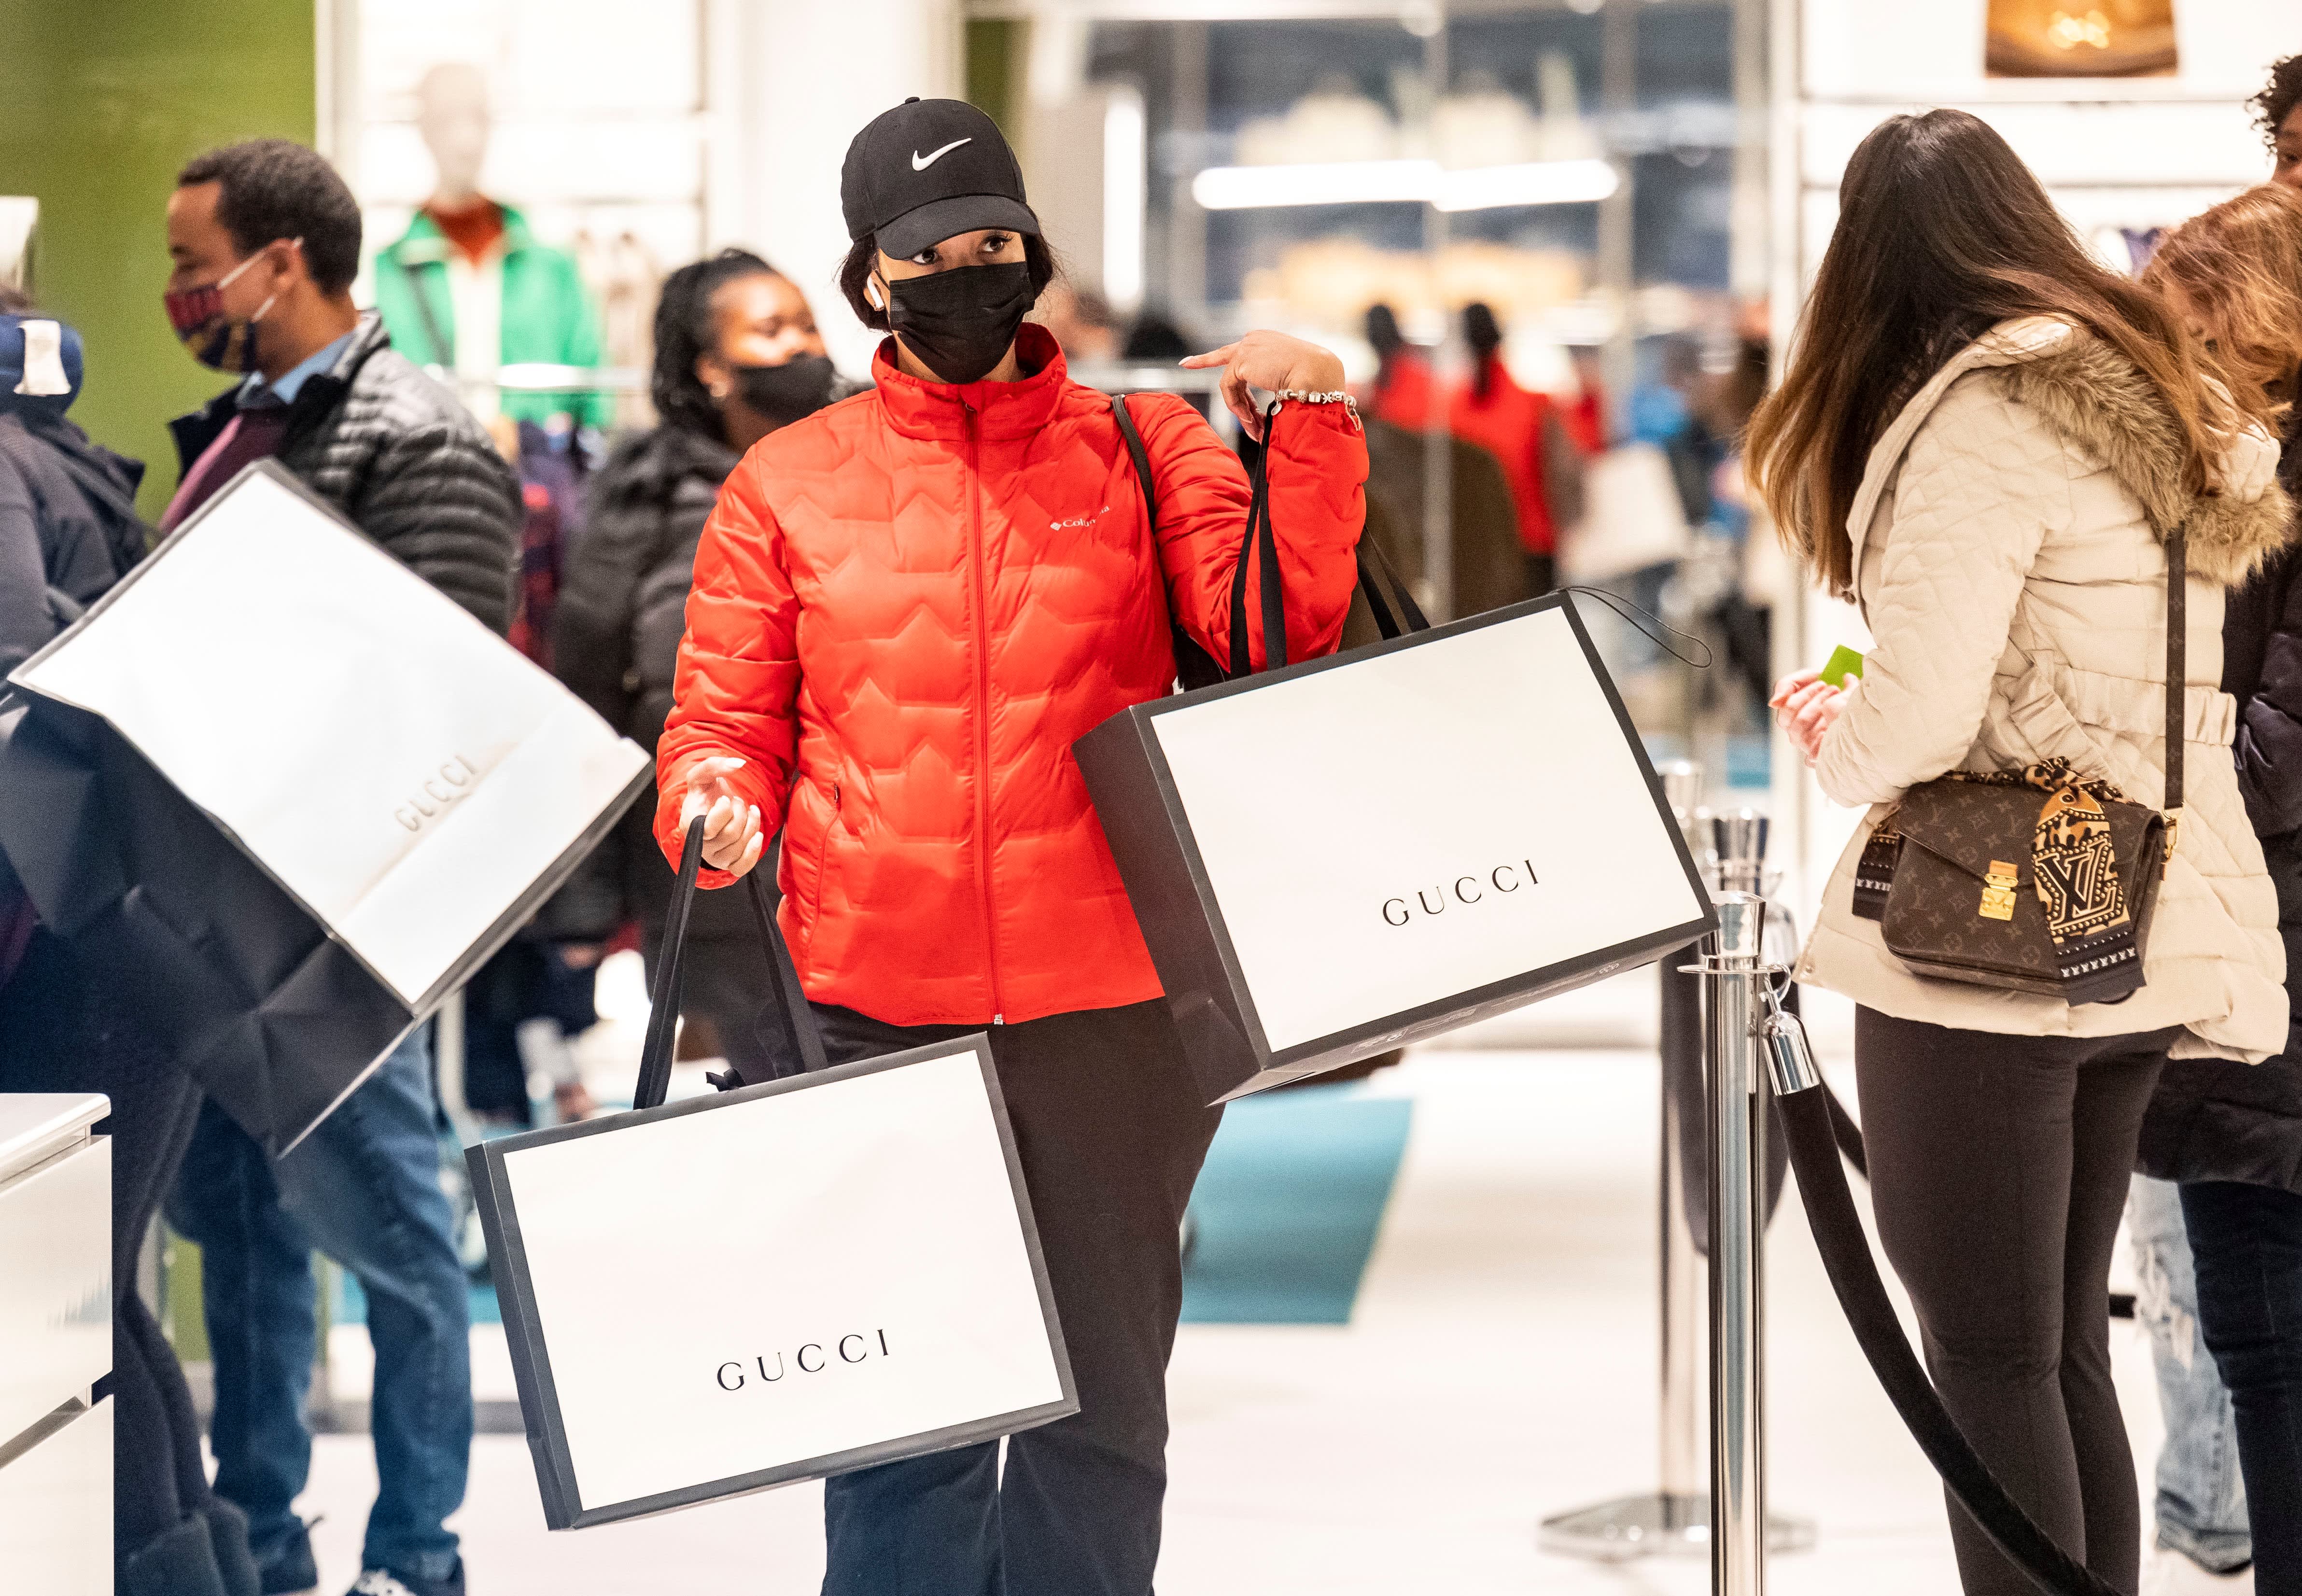
A customer carries her purchases during Black Friday shopping at Fashion Outlets of Chicago in Rosemont of Greater Chicago Area, Illinois, the United States, on Nov. 26, 2021.
Joel Lerner | Xinhua News Agency | Getty Images

Strong consumer demand sparked a wave of CEO optimism about the economy over the next six months, the Business Roundtable said Wednesday, as it revealed the results of its most recent survey.

But the lobbying group, whose members are CEOs of major American companies, cautioned that the survey was completed before the emergence of the new omicron Covid variant, and that the survey measured only the executives’ plans for the next six months.

The Business Roundtable released its fourth quarter CEO Economic Outlook Survey, revealing its headline index had risen to its highest level in the 20-year history of the survey, hitting a value of 124, which is up 10 points from the third quarter. 

On top of that, CEOs reported their plans for hiring increased 13 points, plans for capital investment increased 7 points and expectations for sales increased 9 points. The group cited the release of enormous pent-up consumer demand as a driver of the optimism in corporate boardrooms.

“This quarter’s survey reflects the encouraging signs we’re seeing with the economic rebound as consumers begin to resume travel and spending,” said Business Roundtable Chairman Doug McMillon, the CEO of Walmart. “Continued progress in defeating the pandemic, including new variants, will be necessary to sustain strong growth into the second half of 2022.”

In their first estimate of 2022 U.S. GDP growth, CEOs projected 3.9% growth for the year.

The Business Roundtable survey also asked CEOs for the cost pressures facing their companies. Forty-eight percent identified labor costs as the top cost pressure, followed by 20% identifying supply chain disruption costs and 17% identifying material costs.

Business Roundtable CEO Josh Bolten spotlighted recent legislation on Capitol Hill as one of the reasons for the executives’ economic optimism.

“The recent bipartisan Infrastructure Investment and Jobs Act, which directs much-needed resources to upgrade our nation’s physical infrastructure and broadband connectivity, is an important investment in the long-term health of the economy,” he said. “As the economy reverts to a normal cadence, sound economic policy can help sustain strong growth over the long term.”

The survey was conducted between Nov. 3 and Nov. 22. The World Health Organization labeled omicron a “variant of concern” on Nov. 26.

Read More